

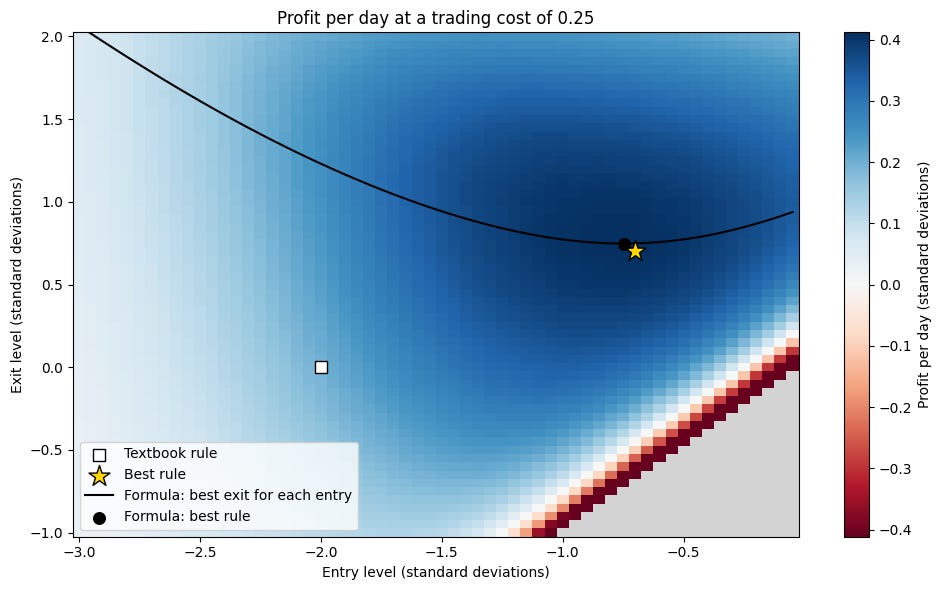
If you trade mean reversion, you probably enter at two standard deviations and exit when the spread is back at its mean. On the same price paths, that rule earns about half of what the best entry and exit levels earn.
The best levels can be calculated from two numbers you already know: your trading cost and the width of your spread.
Here’s everything we’ll cover:
Testing Every Exit: every entry and exit level on one simulated spread
Where to Take Profit: a formula from your cost and your spread’s width
On a Real Spread: testing the optimal rules on a real spread
By the end, you have optimal entries and exits for your own spread.
This article is for paid subscribers. A subscription also unlocks the full archive of over 100 articles and the 24 new articles coming in December. If you are already subscribed, you can keep on reading!